Property Taxes in Kenya: A Complete Guide to Stamp Duty, Capital Gains Tax, and Rental Income Tax
Navigating Kenyan real estate taxes requires clarity on statutory rates, payment deadlines, and digital filing portals. Here is a definitive guide to Stamp Duty, Capital Gains Tax (CGT), Monthly Rental Income (MRI) tax, and county land rates.
Whether you are acquiring your first residential home in Nairobi, building a diversified portfolio of suburban rental apartments, or disposing of commercial land, property taxation directly impacts your net financial returns. The Kenyan tax landscape has evolved rapidly over recent years, with increased digitisation through the KRA iTax and Ministry of Lands ArdhiSasa systems.
Understanding which taxes apply to buyers, which apply to sellers, and which govern ongoing rental income is essential for statutory compliance and accurate financial budgeting.
The Core Property Taxes in Kenya: Summary Matrix
Kenya real estate tax framework encompasses four distinct taxes levied at different stages of property ownership:
| Tax Type | Statutory Rate | Responsible Party | Payment Trigger / Timing | Filing Portal |
|---|---|---|---|---|
| Stamp Duty | 4% (Urban) / 2% (Rural) | Buyer (Purchaser) | Upon transfer instrument lodging | ArdhiSasa / KRA iTax |
| Capital Gains Tax (CGT) | 15% of net capital gain | Seller (Vendor) | Before title transfer registration | KRA iTax Portal |
| Monthly Rental Income (MRI) | 7.5% of gross rent | Landlord (Residential) | Monthly (by the 20th day) | KRA iTax Portal |
| County Land Rates | Varies by county valuation roll | Current Title Holder | Annual municipal property tax | County Revenue System |
| National Land Rent | Set in title lease contract | Leasehold Title Holder | Annual ground rent to national gov | ArdhiSasa / Lands Ministry |
1. Stamp Duty: The Buyer Acquisition Tax
Under the Stamp Duty Act (Cap 480), stamp duty is a mandatory fiscal levy on formal legal conveyance instruments transferring real estate:
- Urban Rate: 4 percent of the assessed property market value for properties situated within municipalities and gazetted urban centers (including Nairobi, Mombasa, Kisumu, Nakuru, Eldoret, and surrounding metropolitan municipalities).
- Rural Rate: 2 percent of the assessed market value for agricultural and rural properties located outside gazetted urban boundaries.
Crucially, stamp duty is calculated on the open market value determined by the Ministry of Lands Chief Government Valuer, not necessarily the purchase price stated on the contract. If the government valuer determines that an apartment contracted at 10 million Kenyan shillings is worth 12 million shillings, stamp duty will be assessed at 4 percent of 12 million (480,000 shillings).
2. Capital Gains Tax (CGT): The Seller Disposal Tax
Under Section 34 of the Income Tax Act (Cap 470), as amended by recent Finance legislation, Capital Gains Tax is levied on the net profit realized upon the transfer or sale of real estate in Kenya.
Key CGT provisions every property owner must know:
- Current Rate: 15 percent of the net capital gain, increased from the previous 5 percent rate to mobilize domestic tax revenues.
- Net Gain Formula: Net Gain = Adjusted Selling Price - Adjusted Acquisition Cost.
- Allowable Deductions: Sellers can legitimately deduct verified acquisition legal fees, stamp duty originally paid, professional valuation fees, advertising expenses, and documented capital improvements (e.g., kitchen remodels, structural extensions, borehole drilling).
- Final Tax: For individual sellers, CGT is a final tax and is not subject to further personal income tax assessment.
3. Monthly Rental Income (MRI) Tax: The Landlord Cashflow Tax
Residential property investors are subject to the simplified Monthly Rental Income regime under Section 6A of the Income Tax Act:
- Tax Rate: 7.5 percent of gross rental income received.
- Eligibility Threshold: Individual resident and non-resident landlords receiving between 288,000 and 15,000,000 Kenyan shillings in annual residential rental collections.
- No Expense Deductions: As a simplified turnover tax, landlords cannot deduct mortgage interest, service charges, caretaker wages, or repairs against the gross rent.
- Strict Filing Deadline: Returns must be filed and taxes paid via the KRA iTax portal on or before the 20th day of the month following collection. Failure to file attracts a 2,000 shilling monthly fine plus statutory interest.
4. County Land Rates and National Land Rent
Property owners hold ongoing annual obligations to both local county authorities and the national government:
Key Takeaways
- 01.Stamp duty is paid by the purchaser at 4 percent of verified market value in urban areas (Nairobi, Mombasa) and 2 percent in rural zones.
- 02.Capital Gains Tax (CGT) is paid by the vendor at 15 percent of the net gain, payable prior to final title transfer registration.
- 03.Monthly Rental Income (MRI) tax is 7.5 percent of gross residential rent, filed electronically by the 20th of each following month on iTax.
- 04.Land Rent goes to the National Government for leaseholds; Land Rates go to the County Government for municipal services.
- 05.Document all capital renovation and transaction expenses diligently, as they reduce your net CGT liability upon future resale.
- County Land Rates: Governed by the Rating Act (Cap 267), land rates are annual local taxes levied on the site value of land. In Nairobi, rates fund municipal waste management, road lighting, and emergency services. A Land Rates Clearance Certificate from the county government is a mandatory pre-condition for any title transfer.
- National Land Rent: Payable annually on leasehold titles to the Ministry of Lands. It represents the annual contractual consideration for leasing public land from the government. Payment is processed through the ArdhiSasa digital platform.
Zuri Estates Team
Property Advisory & Client Coordination
The Zuri Estates Team provides independent property guidance, market intelligence, and acquisition support across Nairobi and the Kenyan Coast. Operating from our Kilimani offices, our desk coordinates developer audits, physical site inspections, and legal conveyancing for homebuyers and investors.
Antony Baragu
Real estate strategist
This article has been reviewed by Antony Baragu to ensure the accuracy, completeness, and validity of all market metrics, property details, and investment guidance.
Related Residences, Developments & Neighbourhoods
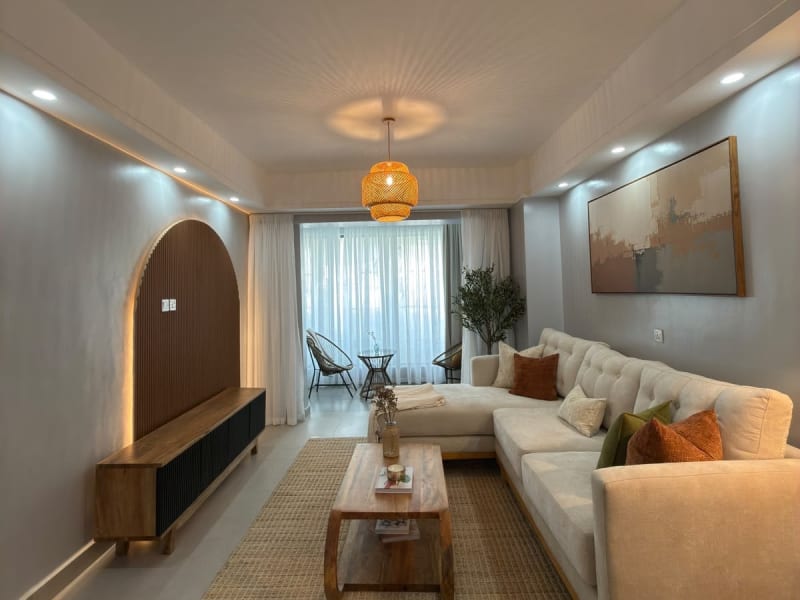
KILIMANI · MENELIK ROAD, OFF NGONG ROAD, KILIMANI, NAIROBI
Emerald Residences
Modern urban living with strong investment potential in Kilimani

WESTLANDS · NAIROBI
Oak West 2 Bedroom Apartment
Contemporary 2-bedroom living in the heart of Westlands.

Westlands · Vihiga Road, Kilimani, Nairobi
Luster Arbor Residency
Modern apartments designed for elegant city living and exceptional long-term investment.

Westlands · Muthithi Road, Westlands, Nairobi, Kenya
Montbleu Residences Westlands
Elevated Living. Timeless Design. Prime Westlands Address.
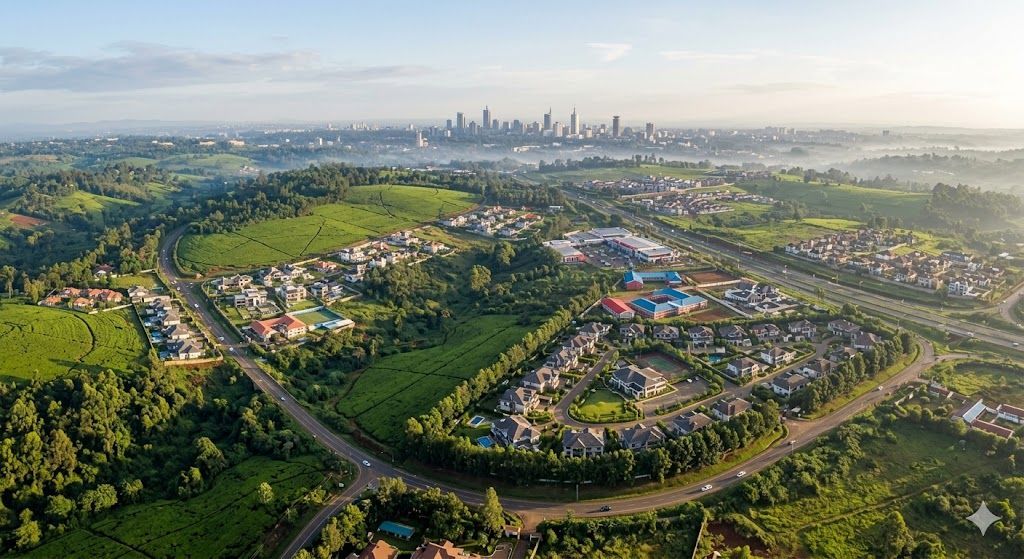
Featured Neighbourhood
Kilimani
Nairobi's vibrant apartment district with exceptional rental demand and investment potential.
Featured Neighbourhood
Kileleshwa
A peaceful, upscale neighbourhood offering elegant apartment living close to Nairobi’s key business districts.
Featured Neighbourhood
Westlands
Nairobi’s premier commercial and luxury residential district with exceptional investment potential.