The Real Cost of Buying an Apartment in Nairobi: A Complete Budget Guide
The purchase price on the brochure is never the final figure. From stamp duty and advocate fees to utility meters and service charge deposits, here is the complete transaction budget for buying an apartment in Nairobi.
The most common mistake first-time apartment buyers make in Nairobi is assuming that agreeing on a purchase price means the financial planning is finished.
You spend months comparing developments across Kilimani, Kileleshwa, and Westlands. You inspect floor plans, scrutinize parking allocations, negotiate the headline price down from KES 12.5 million to KES 12 million, and feel an immense sense of accomplishment.
Then the completion statement arrives from the conveyancing advocate. Beside the agreed purchase price sits a line for stamp duty. Beneath that sits the legal fee and Value Added Tax. Then the valuation fee, registration fee, search disbursements, utility meter allocations, and a demand for six months of upfront service charge deposits. Suddenly, you need an additional KES 850,000 in cleared funds before the keys can be handed over.
This guide provides a transparent, itemized budget framework for buying an apartment in Nairobi. It separates mandatory statutory costs from professional fees and operational handover expenses, giving you the real numbers you need before signing an offer letter.
Summary of Extra Purchase Costs at a Glance
Before diving into each specific cost category, here is how the typical cost breakdown looks for a standard open-market residential apartment transaction in Nairobi:
Transaction Cost Ratios (Nairobi Urban Core)
| Cost Category | Typical Rate or Fee | When It Is Paid | Mandatory / Conditional |
|---|---|---|---|
| Urban Stamp Duty | 4% of property valuation | Prior to title registration | Mandatory (Statutory) |
| Conveyancing Legal Fees | 1.5% to 2% + 16% VAT | Half at signing, half at completion | Mandatory (Professional) |
| Government Valuation | Statutory inspection (nominal) | During transfer processing | Mandatory |
| Title Registration Fee | KES 500 - KES 1,000 per deed | At registry lodgment | Mandatory |
| Service Charge Deposit | 3 to 6 months advance billing | At key handover | Development specific |
| Utility Meter Deposits | KES 25,000 to KES 50,000 | Prior to physical handover | Development specific |
| Snagging & Minor Contingency | KES 50,000 to KES 150,000 | Post-handover inspection | Prudent advisory |
1. Government Stamp Duty: The Largest Single Extra
Stamp duty is a statutory tax levied by the National Government under the Stamp Duty Act (Cap 480) on legal instruments that transfer property ownership. In Kenya, the applicable rate depends entirely on whether the property is classified as urban or rural.
For properties situated within the boundaries of Nairobi City County and other gazetted municipalities, the stamp duty rate is strictly 4 percent of the market value. For rural and agricultural land, the rate is 2 percent.
Valuation May Differ from Purchase Price
Stamp duty is calculated on the market value determined by the Ministry of Lands Chief Government Valuer, not necessarily your negotiated purchase price. If you bought an apartment off-plan for KES 9 million, but by the time of title issuance the government valuer assesses the completed property at KES 11 million, stamp duty will be assessed on KES 11 million.
Payment of stamp duty is processed electronically via the Ministry of Lands digital platform, ArdhiSasa, generating an official e-slip that is paid through the Kenya Revenue Authority (KRA). Title registration cannot proceed without an official Stamp Duty Assessment and verified KRA payment receipt.
2. Legal Conveyancing Fees and Professional Standards
Under Kenyan conveyancing custom, both the purchaser and the vendor appoint independent legal advocates. Do not accept an offer to be represented by the developer's lawyer; independent representation is your only safeguard when reviewing covenants, restrictions, and escrow safeguards.
Advocates' professional fees are governed by the Advocates (Remuneration) Order. For standard conveyancing transfers, fees follow a regulated sliding scale based on the property value:
- First KES 5,000,000: Approximately 2.0 percent of property value.
- Next KES 15,000,000: Approximately 1.5 percent of property value.
- Subsequent balances: Scaled down proportionally, subject to statutory minimum benchmarks.
Remember that legal professional services attract 16 percent Value Added Tax (VAT), which must be factored into your cash planning. In addition to professional fees, your advocate will invoice for out-of-pocket disbursements, which cover official registry search fees, postal and travel costs, land rent clearances, and physical deed lodgment.
3. Practical Worked Budget Example: KES 12,000,000 Apartment
To see how these costs interact in real life, consider a typical two-bedroom apartment purchase in Kilimani negotiated at a contract price of KES 12,000,000 for a cash purchaser.
| Budget Line Item | Calculation Basis | Estimated Amount (KES) |
|---|---|---|
| Agreed Property Purchase Price | Contractual consideration | 12,000,000 |
| Stamp Duty (Urban Nairobi) | 4% of KES 12,000,000 | 480,000 |
| Conveyancing Legal Fees | Scale fee on KES 12M | 205,000 |
| VAT on Legal Fees | 16% of KES 205,000 | 32,800 |
| Official Land Searches & Disbursements | Title, registry & execution costs | 20,000 |
| Registration & Sectional Deed Issuance | ArdhiSasa lodgment fees | 1,500 |
| Service Charge Deposit (Advance) | 4 months at KES 12,500 / month | 50,000 |
| Utility Connection Fees (KPLC & Water) | Meter deposits and administrative setup | 35,000 |
| Independent Snagging Inspection | Professional building surveyor audit | 30,000 |
| Total Cash Required at Completion | Purchase price + all closing costs | 12,854,300 |
In this realistic scenario, the buyer requires KES 854,300 over and above the negotiated purchase price. That represents an additional 7.1 percent in closing costs. Failing to budget for this amount can stall title completion and trigger contractual delay penalties under the Law Society of Kenya Conditions of Sale.
4. Handover Expenses and Moving In Costs
When construction finishes or the completion notice is served, another tier of operational expenses arises before you receive your access fobs and keys:
Service Charge Sinking Fund and Reserve Float: Most modern residential buildings in Nairobi require three to six months of service charge payments in advance. For an overview of what these fees cover, review our detailed guide on apartment service charges in Kenya.
Independent Snagging Audit: Never take handover of an apartment without an independent inspection. Spending KES 25,000 to KES 45,000 on a professional building surveyor to inspect plumbing pressure, electrical circuits, window joinery, and tile hollows pays for itself immediately. For a full breakdown, consult our property handover snagging checklist.
Interior Customization and Window Treatments: Even in ready apartments, developers rarely supply curtain rods, sheer blinds, bathroom vanity mirrors, or light fixtures beyond standard batten holders. Budgeting KES 100,000 to KES 250,000 for initial move-in finishes prevents unexpected credit card debt.
5. Financing Costs: The Mortgage Factor
If you are financing your purchase through a commercial bank or financial institution, closing costs increase significantly. In Kenya, banks do not fold closing costs into the loan facility; they require you to pay them out of pocket prior to disbursement.
Additional mortgage closing items include:
- Loan Facility Arrangement Fee: Typically 1.0 percent to 1.5 percent of the approved loan amount.
- Bank Advocate Legal Fees: The bank instructs its own conveyancing lawyer to draft and register the legal charge over the property. You pay this legal fee in addition to your own advocate's fee.
- Mortgage Valuation: The bank requires an independent valuation report from an approved panel valuer to establish open market and forced sale values, typically billed at 0.25 percent to 0.5 percent of property value plus VAT.
- Insurance Premiums: Mandatory annual fire insurance on the structure and mortgage life protection insurance to clear the balance in the event of the borrower's demise.
Common Mistakes to Avoid When Budgeting
Key Takeaways
- 01.Relying on verbal quotes from sales representatives who omit statutory stamp duty and legal VAT.
- 02.Failing to ring-fence closing funds in a separate savings account, risking default when the completion notice is served.
- 03.Using the developer's legal advocate to save money, thereby forfeiting independent title scrutiny and escrow enforcement.
- 04.Overlooking the service charge operational deposit, which can delay key handover even when purchase funds are cleared.
- 05.Forgetting to verify whether the seller or developer has cleared all historical land rates and land rent on the mother title before completing the transaction.
The Next Step Forward
Before committing your deposit or signing an offer letter, request a formal, written completion statement draft from your independent conveyancing advocate. Ensure every line item, from government duties to utility deposits, is clearly quantified with explicit assumptions.
To understand how buying an off-plan unit compares financially with purchasing a ready, completed home, explore our foundational benchmark analysis on off-plan versus ready apartments in Kenya. If you are evaluating current market inventory, explore our curated portfolio of prime Nairobi residences and upcoming developments across Nairobi.
Zuri Estates Team
Property Advisory & Client Coordination
The Zuri Estates Team provides independent property guidance, market intelligence, and acquisition support across Nairobi and the Kenyan Coast. Operating from our Kilimani offices, our desk coordinates developer audits, physical site inspections, and legal conveyancing for homebuyers and investors.
Antony Baragu
Real estate strategist
This article has been reviewed by Antony Baragu to ensure the accuracy, completeness, and validity of all market metrics, property details, and investment guidance.
Related Residences, Developments & Neighbourhoods
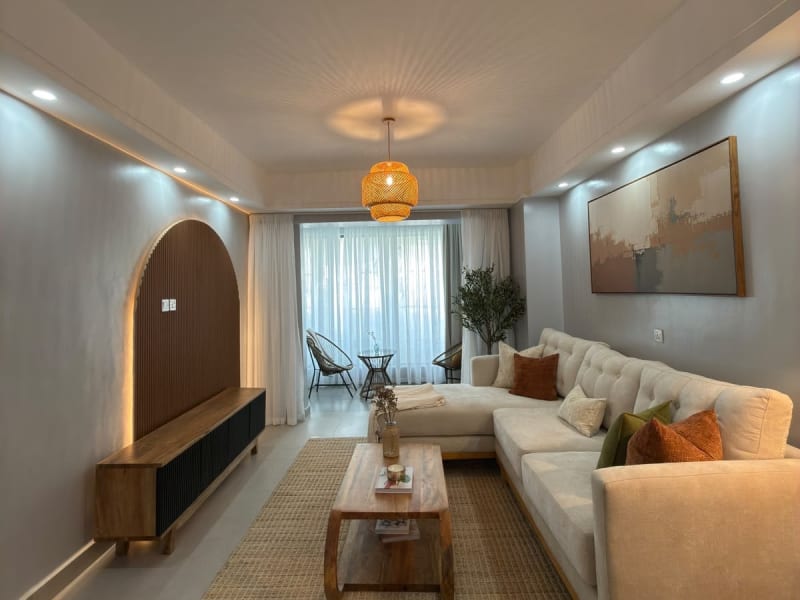
KILIMANI · MENELIK ROAD, OFF NGONG ROAD, KILIMANI, NAIROBI
Emerald Residences
Modern urban living with strong investment potential in Kilimani

WESTLANDS · NAIROBI
Oak West 2 Bedroom Apartment
Contemporary 2-bedroom living in the heart of Westlands.

Westlands · Vihiga Road, Kilimani, Nairobi
Luster Arbor Residency
Modern apartments designed for elegant city living and exceptional long-term investment.

Westlands · Muthithi Road, Westlands, Nairobi, Kenya
Montbleu Residences Westlands
Elevated Living. Timeless Design. Prime Westlands Address.
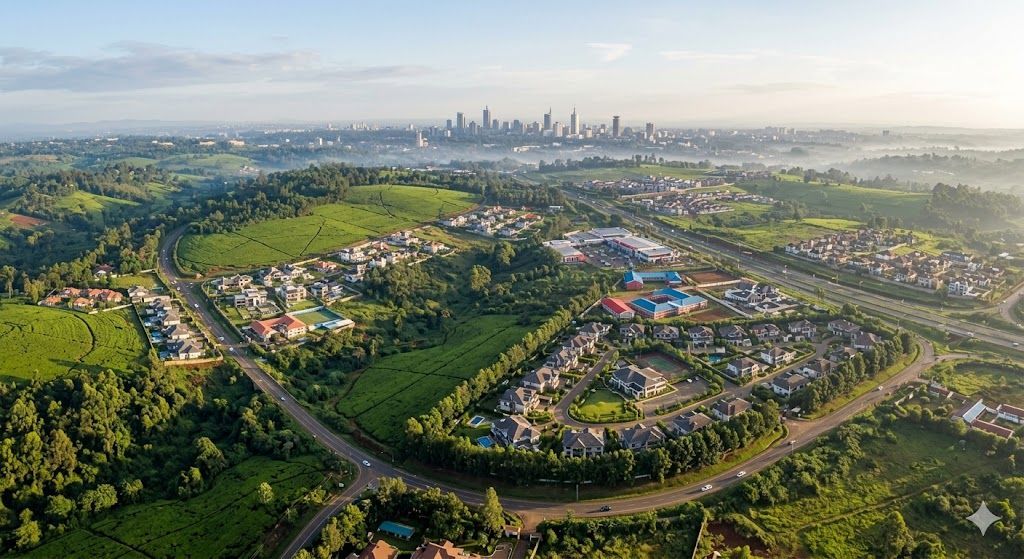
Featured Neighbourhood
Kilimani
Nairobi's vibrant apartment district with exceptional rental demand and investment potential.
Featured Neighbourhood
Kileleshwa
A peaceful, upscale neighbourhood offering elegant apartment living close to Nairobi’s key business districts.
Featured Neighbourhood
Westlands
Nairobi’s premier commercial and luxury residential district with exceptional investment potential.